Marvell's offer of $1,132 a share for Lumentum (LITE) was worth $771 by Monday's close
Marvell is paying 4.5 of its own shares for each Lumentum share. The two companies priced those shares at about $1,132. At the close on Monday 2 November they were worth $771.35, and Lumentum traded $86.95 below even that.
TwiceOver
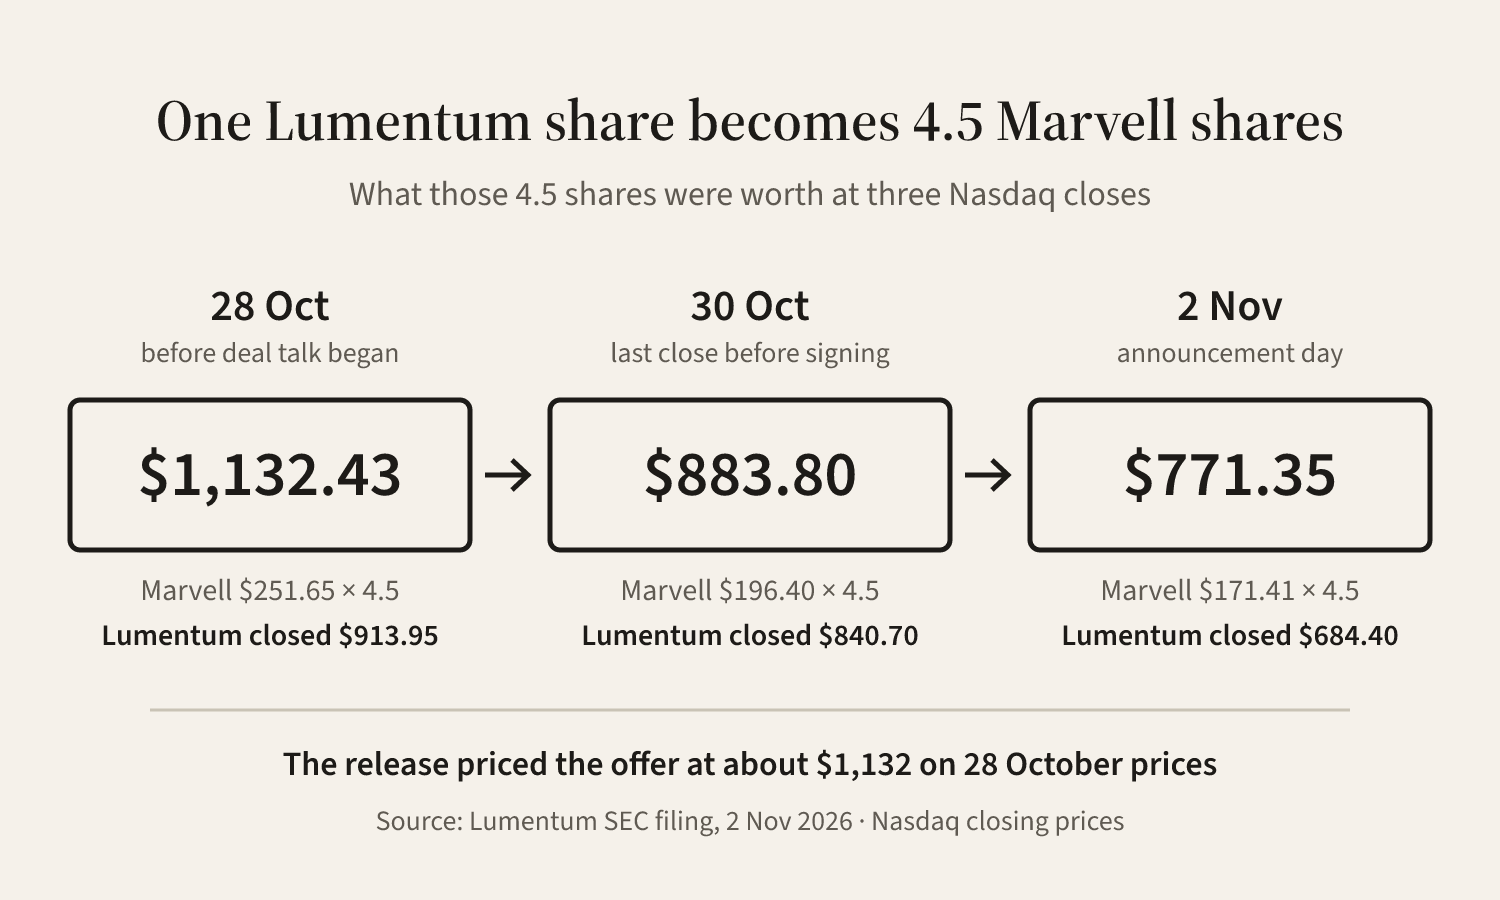
Marvell’s offer for Lumentum is paid in Marvell shares, so the offer’s dollar value moves every day Marvell trades. Each Lumentum share becomes 4.5 Marvell shares when the deal closes. The joint release priced that at “approximately $1,132”, using Marvell’s close on 28 October. At Monday’s close, Marvell stood at $171.41 and the same 4.5 shares were worth $771.35.
1. What the filing says
Lumentum filed the agreement on Monday in a Form 8-K, the report a US company files with the SEC when something material happens. Five lines from it and the joint release carry the deal.
| From the filing and the release | |
|---|---|
| What one Lumentum share becomes | 4.500 Marvell shares, a “fixed exchange ratio” |
| Dollar value in the release | About $1,132, on 28 October closing prices |
| Premium in the release | About 23.9% over Lumentum’s close that day |
| Expected closing | The first half of 2028 |
| Outside date, after which either side may end the deal if it has not closed | 1 November 2027, which can be extended in steps to 1 August 2028 if regulatory approvals are still missing |
The expected closing already sits inside those extensions. The release picks 28 October because it was “the last trading day before market speculation regarding a potential transaction began.” The agreement has no collar, the clause some stock deals add to adjust the number of shares when the buyer’s price moves. So the 4.5 does not move with the price, and the dollars follow Marvell.
2. The same 4.5 shares at three closes
| Nasdaq close | Marvell | 4.5 Marvell shares | Lumentum | Lumentum below the 4.5 shares |
|---|---|---|---|---|
| Wed 28 Oct, before deal talk | $251.65 | $1,132.43 | $913.95 | $218.48, 19.3% |
| Fri 30 Oct, last close before signing | $196.40 | $883.80 | $840.70 | $43.10, 4.9% |
| Mon 2 Nov, announcement day | $171.41 | $771.35 | $684.40 | $86.95, 11.3% |
The last column divides each gap by the value of the 4.5 shares. The release’s 23.9% divides the same $218.48 by Lumentum’s price instead.
Marvell fell 22% in the two trading days after 28 October. The two companies signed on Sunday 1 November. With Marvell at Friday’s $196.40, the 4.5 shares came to $883.80. That is $30.15 less than Lumentum’s close on 28 October. The ratio was not public until Monday, so Friday’s 4.9% is a gap against terms the market had not yet seen.
On Monday, Marvell fell another 12.7% and Lumentum fell 18.6%. Lumentum also reported its own quarter that day. By the close, the offer was worth 31.9% less than the figure in the release.
3. Who earns the $86.95
Lumentum’s price follows Marvell’s because the payment is Marvell stock. A cash deal works differently, as our post on Silence Therapeutics and Merck KGaA’s $20 cash offer shows: there the price drifts toward one fixed number.
In a stock deal like this one, funds trade the gap in two legs. A fund buys one Lumentum share and sells short 4.5 Marvell shares, which means borrowing those shares and selling them now. While the gap holds, a move in Marvell moves both legs together, so Marvell’s price stops mattering to the fund. If the deal closes, the Lumentum share turns into exactly the 4.5 Marvell shares the fund owes, and the fund keeps the gap.
At Monday’s close the gap was $86.95. Against the $684.40 a fund pays for the Lumentum share, the $86.95 is 12.7% for the whole wait into 2028. That is before the cost of borrowing the Marvell shares and any Marvell dividend the fund owes the lender. The 12.7% pays for the wait and for the chance that the deal breaks. If it breaks, the fund holds a Lumentum share and owes 4.5 Marvell shares, and the two no longer move together.
4. What has to happen first
The 8-K lists the conditions. These four carry the most risk:
- Lumentum’s shareholders adopt the agreement.
- Marvell’s shareholders approve issuing the new shares and an amendment to Marvell’s charter.
- The US antitrust waiting period runs out, and “certain other required regulatory approvals” arrive.
- No order from a court or a named government authority blocks the merger.
The agreement lists those other approvals in Marvell’s disclosure letter. The 8-K did not include that letter.
The filing also prices a failure. Marvell pays Lumentum $3.2 billion if the deal ends because regulators block it, or because the outside date passes with only regulatory approvals missing. Marvell pays $5.8 billion if its board stops backing the deal to Marvell’s shareholders, or if Marvell ends the deal to accept a better offer for itself. Lumentum pays Marvell $2.9 billion if Lumentum’s board does either of those. The fees are paid between the two companies, and a fund feels them only through the two share prices.
5. What Monday’s price says
Until the deal closes or breaks, a Lumentum share trades as 4.5 Marvell shares less the gap. While the gap holds steady, a $1 move in Marvell is worth about $4.50 on a Lumentum share. Monday’s 11.3% is the first gap the market set on the public terms. It prices a wait that runs into 2028 and regulators who have not yet ruled.
Sources Lumentum SEC filing, Merger agreement, Joint release, Nasdaq closing prices